 how-to
How Does Whole Life Insurance Cash Value Work?
Table of Contents
- How Does Whole Life Insurance Cash Value Work: The Basics
- How Cash Value Builds Over Time
- Reading a Whole Life Insurance Cash Value Chart
- Cash Value vs. Cash Surrender Value
- When Can You Access Whole Life Insurance Cash Value?
- How to Borrow Against Whole Life Insurance
- What to Watch Out For: Break-Even Periods and Early-Year Trade-Offs
- Frequently Asked Questions
Last Updated: October 9, 2026
How Does Whole Life Insurance Cash Value Work: The Basics
Whole life insurance cash value works as a savings component built into your policy. Part of every premium you pay goes toward insurance costs, and part goes into a cash account that grows over time.
The confusion comes down to one thing: people expect cash value to grow fast. It builds slowly, then picks up speed.
Whole life insurance is a permanent policy that covers you for life and builds cash value at the same time. The NAIC guide to life insurance buyer's resources explains the consumer basics of how these policies are structured.
What Whole Life Insurance Is
Whole life insurance is permanent coverage with a fixed premium and a guaranteed death benefit. It never expires as long as you pay premiums.
The policy has three moving parts:
- The death benefit, paid to your beneficiary when you die
- The cash value, a savings account inside the policy
- The premium, a level amount you pay on a set schedule
How Premiums Are Allocated
Your premium splits into two buckets: one covers the cost of insurance and policy expenses, the other goes into cash value. In the early years, more of your premium pays for costs. Over time that flips, and the growth compounds.
How Cash Value Builds Over Time
Cash value grows in two ways: guaranteed interest and, in participating policies, dividends. Both are slow at first because early premiums mostly cover insurance costs and policy expenses.
Your insurer's policy illustration shows projected values year by year, but those projections assume certain conditions and aren't promises.
Assume a 40-year-old buys a whole life policy with a $500,000 death benefit and a level annual premium of $6,000. The insurer's illustration shows the following pattern (rounded for clarity):
| Policy Year | Premium Paid | Portion to Costs | Portion to Cash Value | Guaranteed Cash Value | Projected Cash Value (with dividends) | Cash Surrender Value | Death Benefit |
|---|---|---|---|---|---|---|---|
| 1 | $6,000 | $4,800 | $1,200 | $1,200 | $1,500 | $0 | $500,000 |
| 5 | $30,000 | $18,000 | $12,000 | $12,000 | $15,000 | $8,000 | $500,000 |
| 10 | $60,000 | $30,000 | $30,000 | $30,000 | $38,000 | $28,000 | $500,000 |
| 20 | $120,000 | $48,000 | $72,000 | $72,000 | $95,000 | $72,000 | $500,000 |
| 30 | $180,000 | $54,000 | $126,000 | $126,000 | $175,000 | $126,000 | $500,000 |
| 40 | $240,000 | $60,000 | $180,000 | $180,000 | $260,000 | $180,000 | $500,000 |
Notice three things. The guaranteed cash value column is the floor; the projected column includes non-guaranteed dividends.
Guaranteed vs. Non-Guaranteed Values
This is the distinction that trips people up most.
- Guaranteed values are the minimum the insurer must credit, no matter what happens. They are backed by the claims-paying ability of the insurer and spelled out in the contract.
- Non-guaranteed values depend on dividends or interest rates that can change. Dividends are not guaranteed and can be reduced or eliminated.
Always read the guaranteed column first, that's your floor. When comparing insurers, compare guaranteed columns side by side: a policy with a lower projected value but a higher guaranteed floor may be more predictable.
How to Read a Policy Illustration or Annual Statement
A policy illustration shows projected values under specific assumptions; an annual statement shows what actually happened.
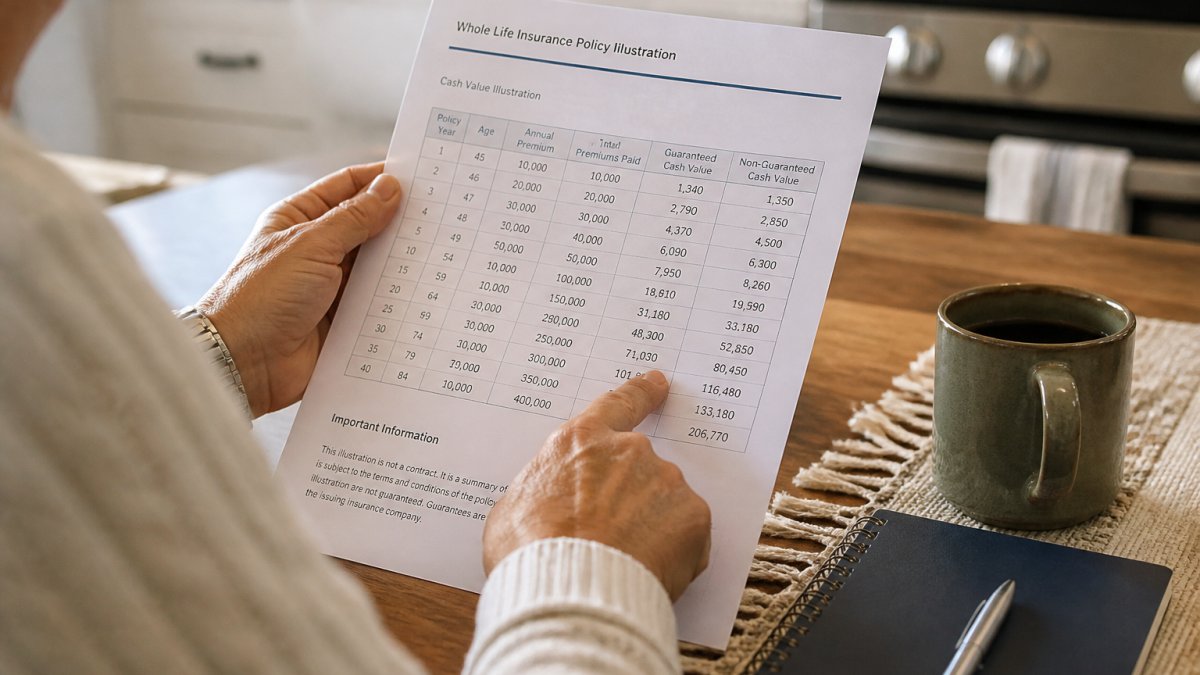
Here's how to scan an illustration:
- Find the policy year column on the left.
- Locate the guaranteed cash value column, not the projected one.
- Check the cash surrender value column next to it.
On your annual statement, compare actual cash value and death benefit to the guaranteed columns.
Reading a Whole Life Insurance Cash Value Chart
If the guaranteed and projected columns diverge in later years, that gap shows how much of the illustration depends on assumptions.
Cash Value vs. Cash Surrender Value
Cash value and cash surrender value are not the same number. Cash value is the total savings inside the policy; cash surrender value is what you'd receive if you cancelled today.
The difference is surrender charges, which most policies charge in the early years. A policy with $10,000 in cash value might only pay out $6,000 if you surrender in year three.
When Can You Access Whole Life Insurance Cash Value?
You can access whole life insurance cash value any time, but the cost changes by year, early surrender charges and low balances make access expensive. Before tapping it, understand the break-even period, the tax treatment of each access method, and what happens if a loan goes unpaid.
The Break-Even Period and Early-Year Trade-Offs
The break-even period is the year when your cash surrender value equals the total premiums you've paid; before that point, surrendering means losing money. For many policies it lands around year 10 to 15 for a policy paid over 20 or 30 years, varying by policy, premium size, and insurer.
What most guides miss: the early years aren't a flaw, they're the structure, you fund costs up front in exchange for lifetime coverage and later growth.
Your Three Access Options
- Borrow against the cash value through a policy loan. You don't go through a credit check. The insurer charges interest, and the loan is secured by your cash value. If you die with an outstanding loan, the death benefit is reduced by the loan balance plus any unpaid interest.
- Withdraw a portion of the cash value. This permanently reduces your cash value and death benefit. Withdrawals are generally tax-free up to your cost basis (the premiums you've paid). Amounts above your basis may be taxed as ordinary income.
- Surrender the policy and take the cash surrender value. You receive the cash value minus any surrender charges and minus any outstanding loan balance. The taxable gain is the amount you receive minus your cost basis. That gain is taxed as ordinary income.
Each has tax consequences. Loans are generally not taxable if the policy stays in force. Withdrawals above your basis can be taxed. Surrender can trigger tax on the gain. The IRS publication on life insurance proceeds covers how these amounts are treated.
What Happens If You Don't Repay a Policy Loan
An unpaid loan doesn't disappear, interest keeps compounding against your cash value. If the loan plus interest ever equals or exceeds the cash value, the policy can lapse, and you may owe tax on the gain even though you never received the money as income.
Suppose your policy has $50,000 in cash value and you take a $30,000 loan. Over several years, interest grows the balance to $50,000.
Tax Consequences at a Glance
- Policy loans: Generally not taxable while the policy remains in force. If the policy lapses or is surrendered with an outstanding loan, the loan amount may be treated as a distribution and taxed to the extent of gain.
- Withdrawals: Tax-free up to your cost basis. Above basis, taxed as ordinary income.
- Surrender: Taxable on the gain (cash surrender value minus cost basis). Taxed as ordinary income.
Tax outcomes depend on your policy status, cost basis, and individual circumstances. Consult a tax professional before accessing cash value.
Affordable Care offers whole life plans with flexible pay schedules, including 10-pay, 20-pay, and 30-pay options, so you can match the break-even timeline to your budget. We also help clients compare these plans against their long-term care and Medicaid planning needs.
How to Borrow Against Whole Life Insurance
Borrowing against whole life insurance means taking a loan from the insurer, using your cash value as collateral, no credit check required.
Here's how the process works:
- Request a loan from your insurer in writing
- Confirm the current loan interest rate
- Decide whether to pay interest annually or let it accrue
- Receive the funds, usually within a few business days
The policy stays in force. Your death benefit is reduced by the outstanding loan balance if you die before repaying.
What Happens If You Don't Repay a Loan
An unpaid loan doesn't disappear. Interest keeps compounding against your cash value.
If the loan plus interest ever equals or exceeds the cash value, the policy can lapse. When that happens, you may owe tax on the gain, even though you never received the money as income. That's the trap most people don't see coming.
What to Watch Out For: Break-Even Periods and Early-Year Trade-Offs
Affordable Care offers whole life plans with flexible pay schedules, including 10-pay, 20-pay, and 30-pay options, so you can match the break-even timeline to your budget. We also help clients compare these plans against their long-term care and Medicaid planning needs.
Frequently Asked Questions
Does a whole life insurance policy have a cash value?
Yes. Every whole life insurance policy includes a cash value component that grows over time. Part of each premium you pay goes toward the cost of insurance and policy expenses, while the rest goes into the cash value. This cash value accumulates on a tax-deferred basis and is guaranteed to grow at a minimum rate set by the insurer. You can access it through loans, withdrawals, or by surrendering the policy. The exact amount depends on your premium, the policy terms, and how long you've held the policy.
How does cash value grow in a whole life insurance policy?
Cash value grows through a combination of your premium payments and any dividends the insurer pays on participating policies. The insurer guarantees a minimum growth rate, so your cash value will increase even if dividends are lower than projected. Early on, most of your premium goes toward policy costs, so cash value builds slowly. Over time, as costs decrease, more of your premium goes toward cash value, and the growth accelerates. Guaranteed values are the minimum you'll receive; non-guaranteed values depend on the insurer's performance.
What happens to the cash value when you surrender a whole life policy?
When you surrender a whole life policy, you receive the cash surrender value, which is the cash value minus any surrender charges and outstanding loans. Surrender charges typically apply in the early years of the policy and decline over time. The amount you receive may be less than the total premiums you've paid if you surrender early. Any gain above your cost basis (total premiums paid) is taxed as ordinary income. Surrendering also cancels your death benefit, so your beneficiaries will no longer receive the payout.
Can you lose money in a whole life insurance policy?
You can lose money if you surrender the policy early, because surrender charges and the front-loaded cost structure may mean you get back less than you paid in premiums. If you take a loan and don't repay it, the outstanding loan plus interest is deducted from the death benefit or cash value, reducing what your beneficiaries receive. However, if you keep the policy in force and pay premiums as scheduled, the guaranteed cash value will eventually exceed total premiums paid. The break-even point often occurs around year 10 to 15, depending on the policy.
Comparing whole life insurance options without a clear picture of costs and guarantees is where most people get stuck. Affordable Care builds whole life plans with guaranteed lifetime coverage, level premiums, and flexible pay schedules designed around your budget and timeline. We also offer fixed-index annuities for principal protection and Medicaid-compliant planning for clients worried about long-term care costs. Get started with Affordable Care and build coverage that grows with you.